
Key Highlights
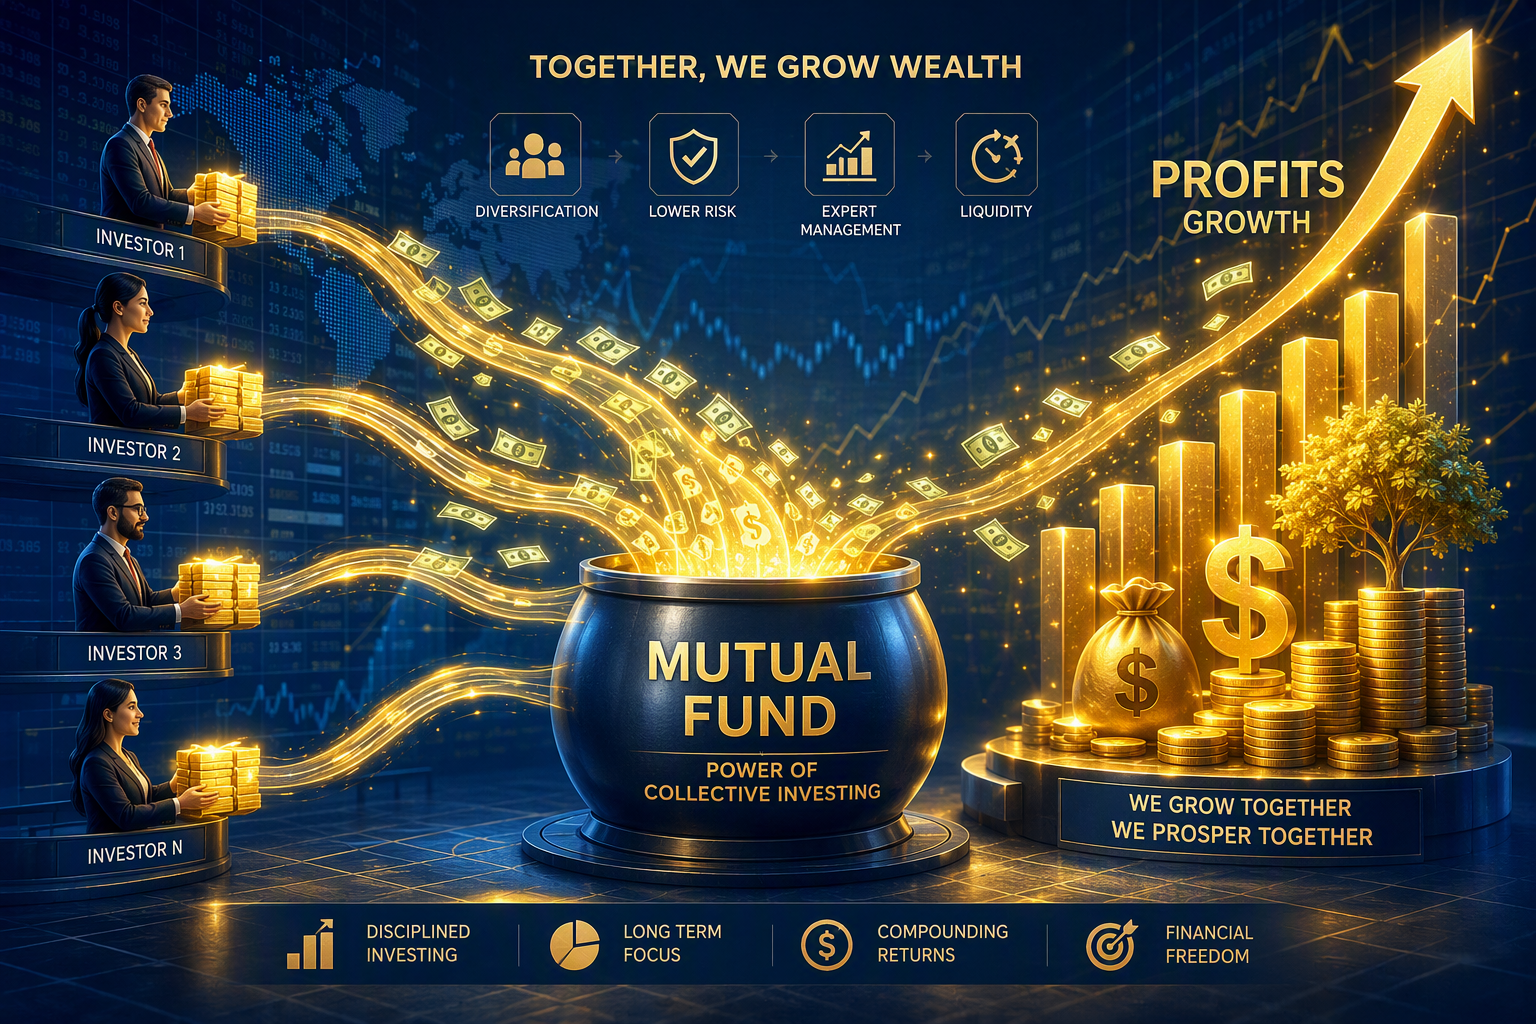
- Mutual funds put your money together with other investors’ money to make a bigger investment pool.
- A fund manager looks after this money. He or she makes investment decisions based on what the fund wants to do, its plans, and how it handles risk.
- The value of your investment will go up or down with the fund’s net asset value and the market value of all the things it owns.
- There are several types of mutual funds. The main types of mutual funds are equity funds, debt funds, index funds, and hybrid funds.
- You may get returns as dividends, income distribution, capital gains, or when your share value goes up.
- Mutual funds can help you reach your financial goals. They do this through diversification, fast access to cash, and professional management.
Introduction
Mutual funds are one of the most common investment products, and they help make things easy for people who want to invest. You do not need to pick each stock or bond. Instead, you put your money into a fund that is managed by professionals. The asset management company handles how the fund works. A team of experts takes care of the money by investing in the right places. This helps you reach your goals and leaves less for you to worry about. If you want to know how the money is collected, invested, priced, and can lead to profits, this guide will show you each part.
Understanding Mutual Funds
A mutual fund scheme is like a pool of money put together by many investors. The money is used to buy things like stocks, bonds, or short term money market instruments. With a mutual fund, you get to be part of more investments than you might get on your own. A mutual fund lets you make use of the money market and boost your chances for good returns.
An asset management company is in charge of the fund and works toward the set investment objectives. A mutual fund is a way for you to put your money in with others. The main idea is to work toward shared financial goals. To get how this works, you can read the basics below.
What Is a Mutual Fund?
A mutual fund lets people pool money together so they can invest as a group. You do not need to buy every security by yourself. Instead, you buy into a mutual fund, and the fund already has a mix of investments. This way, it is easier to get into the market with just one buy.
Each mutual fund has its own investment objectives. Some look to get capital appreciation. Some want to have regular income. Some try to bring growth with some stability. The fund will choose which way to go, and this can make it put money in different asset classes. A mutual fund may be in stocks, bonds, cash equivalents, or money market instruments. All of this depends on what the investment objectives are for that mutual fund.
A fund manager looks after the portfolio. He makes choices every day based on the fund’s rules. So, to say it in a simple way, a mutual fund gives you some ownership in a group of investments. These are picked and managed by a skilled person and have a clear goal.
How Do Mutual Funds Work for Investors?
When you put money in a mutual fund, you buy mutual fund shares. These shares are also called units. The number of units you get will depend on the price of the mutual fund when your purchase goes through. These units show your share of what the mutual fund owns. The value of your units can go up or down, just like the value of the fund’s holdings.
After that, professional management steps in. The fund’s team picks and looks after the investments. They do this based on the plan they told you about. As the value of what they own goes up or down, your money can do the same. You can also get payments from dividends, interest, or capital gains when the fund sells something at a profit.
Taxes matter too. Income tax can apply to your dividends. Capital gains get taxed when the fund gives them out or when you sell your shares for more than what you paid. Your return will depend on both the results of the fund and when you buy or sell.
The Structure and Pooling of Investments
A mutual fund is a pool of money that comes from many investors. This money is put together into one portfolio. When you put your money into a mutual fund, you can get many securities at once with just one investment. Instead of buying just one stock or one bond, you own a part of a bigger group of assets.
An asset management company is the one that makes and runs the fund. It takes care of things like helping with papers, setting prices, sharing updates, and watching over the fund’s portfolio. The company puts investment professionals in charge. These experts manage the holdings to match what the fund wants, like making it grow, bringing in money, or making sure value stays the same.
The fund can have different types of things, such as stocks, bonds, and money market choices. The total asset value of these things will change when markets go up or down. When the asset value changes, it will change what your shares are worth. This is the reason mutual funds can go up or down over time.
The Inner Workings of Mutual Funds
Behind every mutual fund, there are professional money managers at work. They study the market and look at different companies or issuers. These money managers then make investment decisions that match what the fund is supposed to do. Their choices decide how the mutual fund moves with new chances and risks.
Fund companies choose how to spread the portfolio using asset allocation. This means they decide how much to put in stocks, bonds, or cash-like holdings. Their choices depend on market conditions and what the fund is supposed to do. Next, let’s see who makes these moves for fund companies and how they work.
Role of the Fund Manager
A fund manager is the one who takes care of a mutual fund. The fund manager or team watches over what is inside the mutual fund. Their job is to make sure that all the investments match what the fund wants to do. If the mutual fund wants to grow, give income, or be well-balanced, the fund manager will pick things to buy that help reach that goal.
This is why professional management is important. Money managers study the different types of securities. They look at risks and change the portfolio when it is needed. They choose how much of the fund should be in asset classes like stocks, bonds, or cash equivalents. Their choices follow the fund’s plan and rules.
You pay management fees and other costs for having a fund manager take care of the fund. These fees are taken from the fund, which means net returns can go down. A good fund manager might help things turn out better, but how well the fund does still depends on the market and the way the fund is set up.
Investment Strategies Used
Mutual funds use different ways to invest, depending on what they want to do. Some funds try to get capital appreciation. They do this by picking stocks they think will grow over time. Other funds look for regular income. They do this by buying bonds or stocks that pay out dividends. There are some funds that try to get both capital appreciation and regular income. These funds want to give their investors a good total return.
Asset allocation is a top way to plan your money. A fund can put more money in stocks if it wants growth. It can also put more in bonds if it looks for steady income. That mix is what makes the fund act a certain way when markets go up or down. It also shows how much risk the fund may have.
The best strategy for you will depend on your risk tolerance and how long you plan to invest. If you can deal with more short-term changes in the market, growth-oriented funds might be a better option for you. If you want steady income or want to keep your money safe, income-focused or balanced strategies could work well.
How Fund Managers Select Assets
Fund managers pick what is inside a fund by looking at the fund’s goal, set rules, and plan. They do not just buy anything. Each asset has a purpose in the group, like giving growth, income, more range, or keeping things steady.
Their investment decisions often start with asset classes. In stock funds, the managers pick companies that match the fund’s main goal, like growth or value. In funds that focus on bonds, they may go for corporate bonds, government securities, or other debt instruments. It depends on what kind of income they want and how much risk they are ready to take.
The way things are done is also changed by market conditions and the need to follow the fund’s rules. A manager can change how much each item counts, swap out what is in the fund, or adjust how much of each thing the fund owns over time. This means for the people who put money in, the portfolio is being watched and changed as needed. It is not left alone.
Types of Mutual Funds
There are a few types of mutual funds. Each of them is made for a different reason. Some want to help you grow your money. Some want to give you income. Others try to give you both. Your choice of which one to pick should fit what you want, how much time you have, and how much risk you feel good with.
These are the types of mutual funds you may think about.
The most common types of mutual funds are equity funds, debt funds, index funds, and hybrid mutual funds. Each one puts your money in different places and acts in its own way when the market changes. Knowing about these main groups helps you look at your options and choose the best one before you invest.
Equity Mutual Funds
Equity funds put most of their money into company shares. The main goal of these funds is to help your money grow over the long term by aiming for capital appreciation. Stocks can rise and fall a lot. Because of this, equity funds have the chance to give higher returns, but there is also more short-term risk compared to many types of funds that invest in bonds.
You can build a portfolio of stocks in many ways. Some funds look for companies that are likely to grow, while others choose businesses that give regular dividends. The way the mix of stocks is made depends on the fund’s investment objectives and how the manager wants to handle the fund.
These funds are good for people who have a higher risk appetite and can wait for a long time to see returns. If you want your money to grow over many years and feel okay when the market goes up and down, equity funds can be an important part of your portfolio.
Debt Mutual Funds
Debt funds put most of the money into debt securities, not stocks. A debt fund can buy corporate bonds, government bonds, and other tools that make income. These funds look to earn from interest payments. They do not aim for fast price growth.
Debt funds work in this way, so many people use them if they want regular income or lower ups and downs than funds that mostly have stocks. But these funds are not free from risk. The price of bonds can go down. Companies or groups that give out bonds may sometimes not make payments on time. The returns for debt funds depend on both credit quality and interest rates.
Debt funds work in a way that is not the same as equity funds when it comes to risk and possible gain. These funds can be good for you if you want some income, more steady returns, or a fund option that fits short or mid-term money goals.
Hybrid Mutual Funds
Hybrid mutual funds bring together the parts of both equity funds and debt funds in a single plan. You do not have to pick between growth or income. These funds let you have some of both. This can be good for people who want a balanced way to invest.
The main idea is asset allocation. A hybrid fund puts money in both stocks and bonds. It does this following a decided way or by having people adjust it. If stocks help the fund grow, the bond part can give income or make it feel safer. This split helps with the risk part of investing.
For a lot of people who put money in markets, hybrid mutual funds can be a good option. They let you get in on gains when the going is good, but you do not put all your money in stocks. The amount of risk you take with these funds will change based on how much is put into stocks and how much into other things.
Index Funds and Sector Funds
Index funds try to follow a market index as close as they can. They do not try to do better than the market. Index mutual funds want to get the same return as their chosen index before fees. Because they do not buy and sell as much, they often have lower costs. This also means they have fewer transaction costs than other active funds.
This lower-turnover style can sometimes help index funds be better for taxes. For a lot of people, index funds give an easy way to have a diversified portfolio with just one fund. A broad index fund can have shares in many different companies. These companies can be in many types of industries and of different sizes.
Sector funds are not like regular funds. They focus on one part of the market. This could be one industry or a theme. Because they put money in just one area, you can see bigger gains or sharper losses with them. Sector funds do not spread your money out as much. So, their prices can go up and down more than other funds.
Benefits of Investing in Mutual Funds
Many people pick mutual funds to build a portfolio because it is easier. With one buy, you get access to a mix of different investments. You also get professional management to look after your money. This means you do not have to spend your own time to look into and manage each part of your portfolio. So, investing becomes easy for you.
Mutual funds let you take your money out on business days. You can pick them to fit your different financial goals. These funds have some risk, but the way they are set up makes it easier to handle that risk. This is better than just putting your money into one or two things on your own. The sections below will show these benefits in more detail.
Diversification and Risk Management
One thing that makes mutual funds strong is diversification. You do not put all your money in one stock or bond. Instead, you spread your money across many different investments. This can help if one of them does not do well. A loss cannot be removed fully, but it can be less because the risk is not all in one place.
Good risk management comes from asset allocation. A fund can mix growth assets with more stable ones. This is to make the whole process feel smoother over time. For example, if you add debt instruments to the mix, it can help balance out some of the market risk that you get with stocks.
Here are a few ways diversification helps:
- It spreads the risk by putting money into many types of securities, not just one company.
- It can mix things like stocks, bonds, and cash-like items together in one group.
- It can help lower the hit when one investment does not do well.
- It helps you take a more balanced way to deal with market risk as time goes on.
Professional Management
Not everyone has the time or experience to check the markets every day. This is why professional management can help. Mutual funds are taken care of by money managers and investment professionals. They follow the fund’s strategy, watch over its holdings, and make changes when needed.
A fund manager looks at companies, bonds, and market trends. They choose what to buy, hold, or sell while following the rules of the fund. This means you get good oversight, and you do not have to make each investment choice by yourself.
Many people like the convenience as much as the skill that comes with it. You must still pick a fund that fits your goals. After you do that, the people who manage the fund take care of everything every day. This is a good way to keep your money in the market without having to watch it all the time yourself.
Liquidity and Flexibility
One reason people use a mutual fund is because of how easy it is to get their money when they need it. On any business day, you can sell your mutual fund shares, and the fund will buy them back at the next price it figures out. This means your money is not stuck for a long time, like it can be with some other things.
This gives you good flexibility. You can put in money just one time, add more later, put your distributions back in, or ask for a withdrawal when you want. Mutual funds usually set their price at the end of each trading day. So, you do not get the price right away, but you do get a simple way for buying or selling.
For investors, this means you get access without having to trade all the time. You can get in or out when you need to, but some funds might charge an exit load or a redemption fee. This mix of liquidity and structure makes mutual funds a good choice for many money needs.
How to Start Investing in Mutual Funds
Getting started with mutual funds starts when you know what you want your money to do. Do you need growth, want regular income, or look for a mix of both? Your investment goals and the time you have help you pick the right funds.
Once you are sure about the plan, look at the fund options from the asset management company. See if what the fund does fits your financial goals and what is good for you. It is good to check the costs, the risk level, and how the fund is run. All these things really matter.
Here are the next steps to go from an idea to taking action.
Choosing the Right Mutual Fund
Choosing the right fund starts with making sure it fits you. A fund can look good on paper, but it must match your investment objectives. If you want growth, you may pick something with more stocks. If you want income or less risk, a fund with more bonds or a balanced mix could work better.
Your risk tolerance is just as important. Some types of mutual funds go up and down more quickly than others. You should look at how a fund has done in the past, but that should not be the only thing you check. Past results do not mean the fund will do well in the future.
Focus on these points when comparing funds:
- See if the fund’s investment objectives are the same as yours.
- Check if the risk level fits your own risk tolerance and the time you plan to invest.
- Know the types of mutual funds that the fund is in.
- Look at how the fund has performed over time, but remember it does not promise the same results.
Opening an Account
After you pick a mutual fund, you need to open an account. This can be done with the asset management company or by talking to an investment expert. The account lets you buy, keep, reinvest, and sell your mutual fund shares.
Before you decide to put your money in a mutual fund, read the fund papers first. The prospectus will tell you how the mutual fund works, what kind of things it puts money into, the risks that come with it, and what mutual fund fees you will pay. This is important because even small mutual fund fees can cut into what you get back over time.
Pay close attention to transaction costs, expense ratios, and any charges you pay when you buy or sell. A fund with lower costs will help you keep more of your money in your account. Setting up the account is often easy. But the most important thing is to know what you are buying.
Systematic Investment Plans (SIP)
A SIP stands for Systematic Investment Plan. This lets you put a set amount of money into a mutual fund at set times. You do not have to put in a lot of money at once. Instead, you can add money bit by bit over a period of time. This way, investing can feel easy to handle, especially if you are new to it.
A SIP is a good choice if you get a regular income and want to reach your investment goals over a long time. It also helps you follow a plan. You do not need to think about investing every time. The money goes into your investment on its own at set times.
This method helps you stay on track over time. Your returns will still change with the market. But putting money in the fund often can help you keep your eyes on your main goal. You will be less likely to react to every quick move in the market.
Calculating Returns and Profits
Mutual fund returns can come from several sources. You might earn when the net asset value goes up. You can also get capital gains if the securities are sold for more than what they cost. There can also be income payouts from things like dividends or interest, which are handed over to the people who own the mutual fund.
That is why it is important to look at more than just one day’s price when you measure profits. If you want to know how well a mutual fund is doing, it is better to look at the total return over some time. The next sections will show you the main ways the returns are worked out and the words you should know about mutual funds and total return.
How Mutual Fund Returns Are Calculated
Returns in a mutual fund scheme are mostly measured by the total return. This looks at both how the share value has changed during a period of time and adds any dividends, interest, or capital gains distributions you get. Because of this, you get a better picture of the mutual fund’s performance. It is better than just seeing the price change alone.
This is important because a fund can reach its investment objectives by giving income and by growing its value. The total return numbers people see usually mean they put money in when the period started and sold at the end. These numbers also show what happens when all the money paid out, like dividends, was put back into the fund.
Here is a simple text table that shows the idea:
| Return component | What it means |
|---|---|
| Change in NAV | Gain or loss in the fund’s share value over time |
| Dividends or interest | Income paid from underlying holdings |
| Capital gains distributions | Profits distributed after the fund sells assets above cost |
| Total return | Combined result of price change and reinvested distributions |
Understanding Net Asset Value (NAV)
Net asset value, or NAV, shows the price of each mutual fund share or unit. This number is key for people who want to invest. It helps you see the current asset value when you buy or sell a mutual fund. When the things a fund owns go up or down in price, the net asset value will move in the same way.
The way you work out the asset value is by taking everything the fund owns and adding it up. Then, you take away what the fund owes. After that, you divide this amount by the total number of units. So, the market value the fund holds, after all costs are taken out, gets spread out across every unit each person owns.
NAV is worked out at the end of each trading day after the markets close. This is why mutual funds are not traded like stocks during the day. When you buy or sell a mutual fund, the deal is done at the next NAV. It is not based on a live market price at the time you place your order.
Dividends, Capital Gains, and Income Distribution
Mutual funds can help people make money in a few ways. One way is from dividends or interest that comes from the stocks and bonds in the fund. When the fund gives this money to the people who own it, that is called income distribution. Some people take this money in cash. Other people choose to put it back into the fund.
Another way to get money is from capital gains. A fund gets capital gains when it sells something for more money than it paid. If all the gains are more than the losses, the fund may give money from capital gains distributions to the people who own shares. These payments can help grow your total return, even if you do not sell your own shares.
If you are someone who wants regular income, these distributions can help you. But they might also cause tax effects. So, you should know if your fund is there for growth, income, or both.
Fees and Charges in Mutual Funds
Fees can lower your investment results, so you need to watch them closely. Mutual fund charges usually come out of the fund, not straight from you. Because of this, it is easy to miss them. Even if there is a small cost difference, it can change your returns over time.
The main costs here are expense ratios, management fees, sales loads, and other transaction costs. A fund that has higher fees will need to perform better just to make the same return as one with lower costs. Let’s talk about the charges you will see most often.
Expense Ratio and Management Fees
The expense ratio shows the yearly percent that a fund takes for its running costs. This covers things like management fees and other costs needed to keep the fund going. The money comes from the fund’s own assets. So, your returns go down, but you do not need to pay anything extra for it.
Management fees are the money you pay to the fund manager and their team. They look after your portfolio. Active funds cost more. This is because they need more research, more trading, and more decisions. Index funds have lower expense ratios. This is because they follow a benchmark and do not trade as much.
These mutual fund fees are important because they change the fund’s performance after costs. The transaction costs in a mutual fund can build up inside it. When you look at different funds, lower fees can leave you with more money from returns, especially if you keep your money in the fund for a long time.
Entry Load, Exit Load, and Other Costs
Some mutual funds ask you to pay fees when you buy or sell shares. This fee is known as a load. When you first buy shares, you may have to pay an entry load. People also call this a front-end load. An exit load is charged when you sell shares. This is sometimes called a back-end load or deferred sales charge. These fees can take away from the money you put in or the money you get back.
Not every mutual fund uses these fees. A no-load fund will not make you pay a sales fee when you buy or sell. But, you still might have to pay other mutual fund charges. A few funds, like municipal bond funds, also give tax benefits. These can let you get income that is not taxed by the federal government.
Watch for these costs:
- There is an entry load that you have to pay when you buy shares.
- There is an exit load that you have to pay when you sell or redeem shares.
- The mutual fund will have ongoing transaction costs inside the portfolio.
- You can find other mutual fund charges listed in the prospectus.
Comparing Mutual Funds to ETFs
Mutual funds and ETFs both give you a way to invest in a group of different securities. Both can help you get broad diversification. They can follow a plan that is active or based on an index. At first, they might look much the same. But the way you buy or sell them and how you get prices is not the same.
The main difference is that ETFs are bought and sold on stock exchanges all day at the market value. Mutual funds only have their price set one time each day. The costs, starting amounts, and how easy it is to use them can be different too. Here is how these things can matter for real people who invest.
Key Differences Between Mutual Funds and ETFs
Mutual funds and ETFs both put together money from many people. But the way you buy and sell them is not the same. You get mutual fund shares straight from the mutual fund. When you want to sell, you give them back to the fund. The price for this is set after the trading day ends. ETFs, on the other hand, can be bought or sold any time during the trading day, just like you do with stocks.
This difference has an effect on prices and how flexible each option can be. ETFs let people see the price in real time. They also often need a lower amount of money to get started. Mutual funds can be a good pick for people who want to put money in again and again. They also help with putting dividends right back into the fund and planning for money to come out at set times. Management fees can also not be the same. They change with whether the fund is active or passive.
Key differences include:
- Mutual funds get their price only one time in a day. ETFs can be bought or sold all day long.
- ETFs are traded on exchanges at market prices.
- Mutual funds are often better if you want to set up automatic investing.
- The costs and management fees are not the same. They change with each fund style.
Suitability for Different Types of Investors
Suitability is based on the way you like to invest. If you like an easy, hands-off process with investing that is done for you and easy-to-use account tools, mutual funds can be a good choice. If you want to, trade during the day and see prices live, ETFs may be better for you.
Your investment objectives play a big role. If you want to save for a long time, you may want something easy to use and not care much about fast trading. But if you have a bigger risk appetite or like to buy things on an exchange, you may feel that ETFs are better. There is not one choice that is always the best. The right one is the one that meets your needs.
If you are not sure, you can talk to investment professionals or fund companies. They can help you learn about the real differences. The most important thing is to pick the structure that fits how you invest, how often you want to trade, and what features are most important to you.
Mutual Funds for Beginners
Mutual funds are a good choice for someone who is new to investing. They are simple, and they spread your money out to different stocks and bonds. You do not have to pick each stock or bond on your own. The way the fund is set up gives you some basic help with managing risk right from the start.
They also make it simple to link investing with your clear financial goals. If you are new to this, a few easy steps can help you feel sure as you start and not make common mistakes. The next two parts tell you more about this.
Easy Steps to Start Investing
Starting with a mutual fund does not need to be hard. First, you need to think about what you want your money to do. Then, pick a mutual fund scheme that fits your goal. Once you do that, open an account with an asset management company. You can also use online platforms that let you get into these funds.
If you like to take things slow, you can use a SIP to put money in often. You do not have to give a big amount all at once. A SIP can help you manage your money better, and it can teach you to be steady with your savings over time. The main goal is to start with a plan that feels real and good for you.
A simple checklist can help:
- You need to know your goal before you pick a fund.
- Check the fund’s goal, its risk, and what it costs.
- Open your account in a way that you trust.
- Set up a SIP if putting in money often works for your budget.
Common Mistakes to Avoid
New investors sometimes make mistakes they could have kept away from. They do this when they only pay attention to short-term market value changes. A fund can go up or down fast. But, if you react to every move, that can hurt your investment decisions. It is good to pick mutual funds with a clear plan in mind and give them enough time to grow. These funds usually do better that way.
Another common problem is not thinking about costs or the risk level. High expense ratios can eat into your returns over time. A fund might look good because of its past performance, but it might not be right for your risk tolerance. A good fit matters more than just getting excited about a fund.
Try to avoid these mistakes:
- Many people chase recent winners and do not look to see if they fit for the long run.
- Some ignore expense ratios and other costs that can add up over time.
- People can choose funds that do not match their own risk tolerance.
- Others invest without knowing the fund’s main goal.
Risks Associated with Mutual Funds
Mutual funds do not have a guarantee. They are not insured, so you can lose money when you invest. With market-based products like these, there is some risk you need to think about. The risk can change the return you get and may even mean your first money goes down in value. What the fund owns can change the type and level of risk.
Some risks can come from big changes that happen in the market. Other risks are tied to the bonds, the people or groups that give out the bonds, or changes in interest rates. Because funds put money into many asset classes, the risk for these funds can be very different. The sections below talk about the main risks you need to know.
Market Risk and Credit Risk
Market risk means there is a chance that a fund can drop in value if the whole market goes down. This risk often shows up in equity funds. That is because the prices of stocks can rise or fall very quickly. Even if you have a stock fund made up of different stocks, it can still lose value if the market as a whole is going down.
Credit risk happens often in funds that have debt securities. This is when there is a chance that the company or group that gave out a bond cannot pay the interest or full amount back on time. When you put money in corporate bonds, you could get this risk if the company starts to face money trouble.
Both kinds of risk can change what you get back, but they show up in different ways. Market risk has to do with price changes all over the market. Credit risk is more about the money situation of the people who give out the funds. If you know which risk is stronger in a fund, you can set better ideas for what it might do.
Interest Rate Risk
Interest rate risk is something that can hurt bond and income-focused funds. When interest rates go up, the price of old bonds often goes down. So, funds that have debt instruments may lose value, even if the companies or governments that issued them still pay as planned.
This is important for funds that buy government bonds, company debt, and other fixed-income things. How this happens can change based on the time to pay back, how long they hold the bond, and what kind of things are in the fund. But the main idea is the same. When rates go up, it can push down the prices of bonds.
If you use bond funds to get steady income or to keep your money safe, you need to know about this risk. Debt funds can still help in your portfolio. But the value is not always the same. When rates change, it can change how they do in the short term and what people expect from them.
How to Manage and Reduce Risks
You can’t get rid of all the risk in investing, but you can try to handle it better. The best way to do this is with asset allocation and making sure you have a mix of different things in your portfolio. When you spread your money over many types of investments and fund categories, you don’t depend too much on just one area of the market.
Your investment goals are important to keep in mind for this process. If you want growth in the long run, you may want to have more stocks. If you need steady money or want less risk, more bonds or balanced funds could be better. You can mix different types of mutual funds to build a portfolio that can handle many market changes.
Helpful risk management steps include:
- Use diversification instead of focusing only in one area.
- Match your asset allocation to your goals and the time you have.
- Combine different types of mutual funds when needed.
- Choose funds that match your comfort level with market swings.
Evaluating Mutual Fund Performance
To see how well a mutual fund is doing, you need to look at more than one number from a short time period. It is good to know where the mutual fund returns come from. A fund can make money in several ways, like share price growth, income, or capital gains distributions. You should check if these results match what the fund’s performance goal says.
Past results can help you see what has happened before. But they do not tell you what will happen in the future. Rating agencies and research tools can help when you want to look at different choices. It is important to use these tools in the right way. The next parts will show you how to do this the smart way.
Using Rating Agencies and Research
Rating agencies can help you when you look at mutual funds. They get data on a fund’s performance, risk, cost, and type. This lets you see many options fast and compare them. You can save time when you try to narrow your choices.
Ratings should be your first step, not your last. A high score often shows how a mutual fund has done before, but this was because of the market conditions at that time. A mutual fund that did well in the past may not stay on top if market conditions change.
Good research can help you a lot. Be sure to read the prospectus. Look at the fund’s goal and check the fees. Ask yourself if this plan is right for your mix of investments. Ratings can help you see how funds stack up, but what matters is whether this fund is better for you than others.
Past Performance vs Future Potential
How a fund did in the past shows you what it was like before. It does not tell you what will happen next. Past performance can help you see if a fund was up and down or if it stayed steady. It can also show if it gave out strong capital gains or income before. This history can help you know more, but it is not a forecast.
What can happen in the future does not only rely on old returns. A fund’s plan, its costs, how the manager works, and what is coming next are all important. Market value can shift fast, and even a fund that did well at one time can have a hard time when the market changes.
That is why it is important to look at total return with care. Use what has happened in past years to see trends. But do not think the top results from yesterday will stay best. A better way is to look at total return in the past and how it fits your needs, its cost, and your long-term goal before you put in your money.
Conclusion
To sum it up, mutual funds give people a clear way to put their money to work. These funds come with some big plus points, like giving you many choices、in your investments, offering professional management, and being flexible with how you use them. When many people join their money together, they each get to invest in more things than they might on their own. If you understand how mutual funds work—from the fees you pay to how you check their results—you can feel good about the choices you make. It does not matter if you are new at this or if you have done it for a while; starting with mutual funds can help you grow your money. Take time to look at all the choices, and if you feel ready to start, think about talking with someone for a free meeting to help you along the way.
Frequently Asked Questions
Are mutual funds safe for first-time investors?
Mutual funds can be a good choice if you are new to investing. You get professional management and a mix of many stocks or bonds in one product. But these are not risk-free. The amount of risk depends on your risk appetite and the kind of fund you pick. To be safe, pick a fund that fits your goals.
Can I withdraw money from a mutual fund anytime?
In most cases, yes. A mutual fund gives you easy access to your money. You can sell mutual fund shares on any business day. The price is set at the next calculated value. Your money is given to you after the trading day ends. Keep in mind, some mutual funds may have an exit load or fee when you take your money out.
What fees should I look out for when investing?
You should look at the expense ratios, management fees, and any sales charges like an entry load or exit load before you go for that mutual fund. All of these mutual fund charges can take away from your return over time. Make sure to read the prospectus for the mutual fund so you know what it will cost and how the fees work.

