
Key Highlights
- Money market mutual funds put their money into short-term debt securities. They try to keep the asset value steady.
- Savings accounts are a type of deposit accounts that banks offer. They are made for safety, easy access, and steady interest rates.
- In some market conditions, money market mutual funds can give better returns than simple savings accounts.
- Both choices are liquid, so you can get your money out fast, but their withdrawal rules and timing may not be the same.
- Savings accounts have the safety of Federal Deposit Insurance Corporation backing. Money market mutual funds instead have a low level of market risk.
- The best choice for you will depend on how fast you want to get your money, what returns you hope for, and how much risk you feel good with.
Introduction
If you are thinking about where to keep cash, you can look at money market mutual funds and savings accounts. These two are common ways to save for short-term needs. But they are not the same. A money market mutual fund is an investment product, but a savings account is something you get at a bank. This changes how safe your money is, how fast you can get it, and how the interest rate or yield is set. So you might wonder, what is the best place to keep your cash? It will be different for each person. It depends on what you want your money to do and when you will need to use it.
Understanding Money Market Mutual Funds and Savings Accounts
At the basic level, savings accounts and money market mutual funds are both good ways to keep cash that you may need soon. People use them to save for short-term goals, keep an emergency fund, or hold money that will be spent soon.
Money market mutual funds and savings accounts are not the same thing. A money market mutual fund puts money in short-term debt. A savings account is a deposit account you can open at a bank. That main difference affects how you get your money, how safe your money is, and how much you can earn. The sections below show this in a clear way.
Definition and Purpose of Money Market Mutual Funds
Money market mutual funds are a type of mutual fund you can use for cash that you want to keep ready for the short term. These funds put money in high-quality debt securities, not in stocks. Their main goal is to protect your money, make it easy for you to get it when you need, and to give you a little extra income.
These funds collect money from people who invest in them. Then they buy money market instruments. These are things like treasury bills, commercial paper, repurchase agreements, and certificates of deposit. The things the fund holds usually have short maturities and do not last longer than one year. Because of this, the money market fund is made to stay steady. It is set up to not have big changes in price.
In many retail cases, money market mutual funds try to keep the asset value steady at $1 for each share. This means your balance will mostly go up from earnings, not from changes in share price. This makes them good for things like emergency savings, money to use soon, and holding cash in a brokerage account.
Definition and Role of Savings Accounts
Savings accounts are a type of deposit accounts at the bank. You can use them to keep your cash safe and also earn interest payments on your money. These accounts are part of the banking system, not investments. You put money in, the bank holds it, and you get interest over time.
For a lot of people, savings accounts are the way to go when they want to set up an emergency fund. These accounts are easy to use and do not take much time to open. They also work well with your usual banking. A savings account usually has some extras that you will not get with money market or mutual funds, like ATM access or help if you go over the limit.
Savings accounts are a type of bank deposits. They focus on keeping your money safe instead of giving you the best returns. This means you often get lower returns than with some other cash choices. But if you want to feel calm every day and get your money fast when needed, savings accounts are a good place to keep your short-term cash.
Comparing Money Market Mutual Funds with Traditional Mutual Funds
Not every mutual fund works the same way. A money market fund helps protect your money and lets you get to it fast. Other mutual funds, like many traditional ones, try to help you grow your money or make income over more time. This means the risk, what you get back, and how prices go up or down will not be the same. A market fund, money market, or other mutual funds each have their own purpose and risk.
Here are a few things that make money market mutual funds different from bond funds and other mutual funds:
- They put money in short-term debt that is good quality, not in assets that last a long time.
- They be interested in being steady instead of trying to get big capital gains.
- They often want the share price to stay steady and not go up or down a lot.
- They be used to handle cash, not to help it grow over a long period.
- Their investment objectives are to give access and keep things from getting too up or down.
So, if you want to have steady access to cash, a money market fund may be a better choice than stock funds or bond funds. If you are looking for your money to grow over time, other mutual funds could be a more good fit for you instead of a money market fund. Each kind of market fund has its own way to fit your needs.
How Money Market Mutual Funds Operate
A money market fund works by gathering cash from people who want to invest. It puts this money into debt securities with short maturities. A market fund picks these for their stability, how easy they are to turn into cash, and the income they can give. It is not meant for long-term growth but for safety and quick access to your money.
Money market mutual funds use safe ways to invest. Their goal is to keep asset value safe while giving payouts, and most payouts can be monthly. The yield of these funds can go up or down with changes in interest rates or market conditions. To know why this happens, you can look at the types of things they buy and the rules they follow.
Investment Strategies in Money Market Mutual Funds
The way money market mutual funds work is simple. The fund managers aim to keep your money safe, let you get to it easily, and try to earn a bit of income. They choose high-quality places to put your money, and only for a short time. Their plan is not to get big or risky profits. It is really about making sure you do not lose value, and you still get a good rate of return on your cash reserves.
To do that, fund managers usually:
- Buy short-term types of securities that have little change in price.
- Spread what you hold across many issuers. This can help lower the chance of big losses.
- Keep maturities short. This helps keep your money easy to get when you need it.
- Change what you own when rates or market conditions shift.
The main good things about this careful setup are clear. You get chances to use your money every day in many cases. There is a low risk because of how it is made. The returns can also be better than regular bank savings. Still, the amount you earn can change. This is because returns go up and down with current interest rates, not because they are promised like a bank deposit.
Types of Money Market Instruments Used
Money market mutual funds put money into a small group of short-term debt that do not stay for long. The funds pick these money market instruments because they want quality, liquidity, and a short duration. This way, the funds can help people get steady access to their money and keep a stable net asset value.
Common holdings include:
- Treasury bills that the U.S. government gives out
- Commercial paper from big, trusted companies
- Repurchase agreements that use government securities as backing
- Certificates of deposit that banks give
- Short-term bonds from a government agency or company
Each instrument in the money market has its own job. Treasury bills and those holdings backed by the government help keep money safe. Commercial paper can help give a better return. Certificates of deposit bring in more short-term income. Repurchase agreements make sure there is enough cash when needed. When you put these together, you can see how money market funds try to balance access, steadiness, and income. They do this for people who want to use their money soon.
Regulatory Framework for Money Market Mutual Funds in India
Money market mutual funds follow rules made to keep investors safe and help keep things steady when the market changes. In the U.S., the exchange commission, known as the Securities and Exchange Commission, is the group that checks these funds. The rules decide how good the money market fund’s investments have to be, how much of the fund’s money should be easy to get to, and how prices should be set. These steps help the funds work well even when market conditions change.
One big part is how funds deal with stress in the market. Retail and institutional funds may have to use liquidity fees or may even set up short redemption gates if weekly liquid assets drop under certain levels. These steps help funds stay stable when there is market stress. Government funds can decide if they want to use these features during times of market stress.
The given information does not show detailed rules for India. But, it does show one main thing. The rules focus on three key areas: keeping enough cash, holding high-quality items, and using short-term debt like government securities. The goal is to help people feel sure about their money and stop big problems from happening.
Features of Money Market Mutual Funds vs Savings Accounts
When you look at money market mutual funds and savings accounts, three things are important. These are how much you can earn, how easy it is to get your money, and how safe your money is. Both are seen as low risk ways to keep cash, but they work in different ways.
Money market mutual funds can sometimes give you a higher rate of return than savings accounts. Savings accounts, though, are good for keeping your money safe and easy to use. You can get your money from both, but the way you take it out may be different. Up next, we will talk more about things like interest rates, how you use your money, and risk. This way, you can find out if money market mutual funds or savings accounts work better for your cash needs.
Interest Rates and Returns Comparison
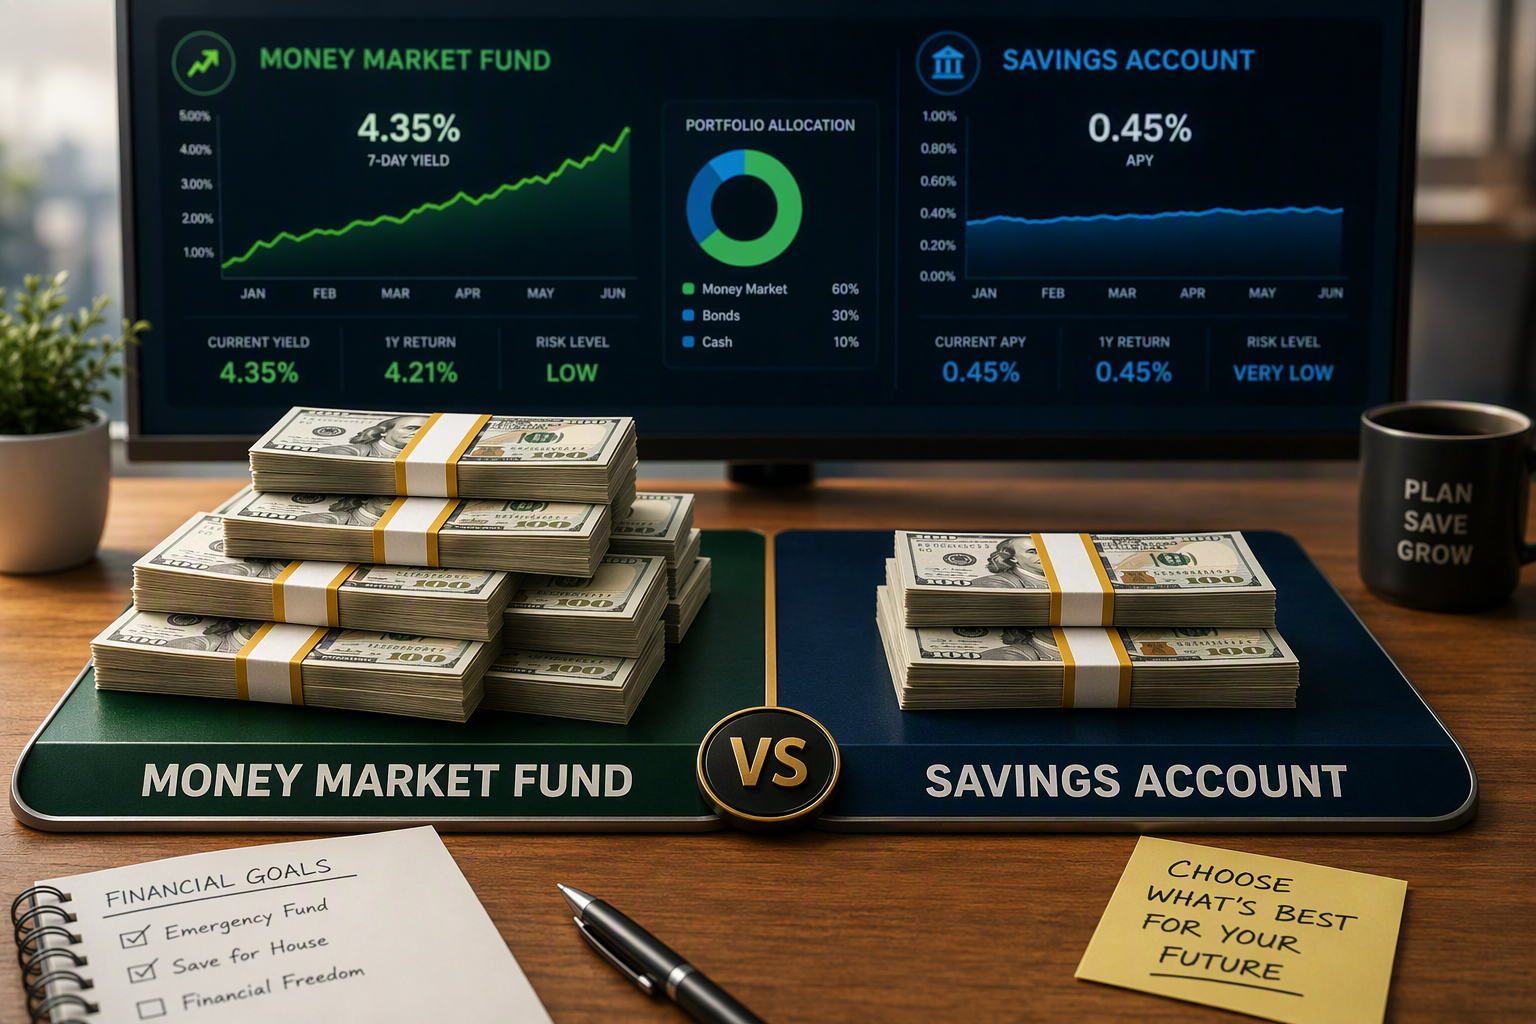
The return difference is what makes people choose between options. Savings accounts show their interest rate with APY. Money market mutual funds use a 7-day SEC yield. This shows the rate of return each year, based on what has been paid out in the last week after expenses. So, the numbers for savings accounts and mutual funds are not shown the same way.
In many market conditions, money market mutual funds can give you more than savings accounts. But they do not have a fixed goal or promise. Their yields can go up or down. The Federal Reserve, fund type, and the securities they hold all have an effect on the money market mutual funds’ returns.
| Feature | Money Market Mutual Funds | Savings Accounts |
|---|---|---|
| Return measure | 7-day SEC yield | APY |
| Typical pattern | Can be competitive and sometimes higher | Often lower returns |
| Guarantee | No guaranteed yield | Bank-set interest rate |
| Change frequency | Moves with market conditions | Changes at bank discretion |
Access, Liquidity, and Withdrawal Options
Both choices give you strong liquidity, but they work in different ways. A savings account gives you easy access to your money at the bank. A market fund is used to manage cash in an investment account. This difference changes how fast you can move your money and the tools you use for that.
With money market mutual funds, you get quick access to your money because the funds follow simple rules and keep short-term holdings. Sometimes, you can take out money the same day. Savings accounts may be easier when you want to spend your money, since they are part of your bank account and feel familiar.
Here is the real change in the ways you can take out your money:
- Savings accounts may let you get cash with an ATM or move money straight to the bank.
- Money market mutual funds often need a broker to buy or sell.
- A fund’s weekly liquid assets help to cover when people take out their money.
- In very hard times, some funds may charge fees or limit how much you can take out.
So, both savings accounts and other things like them are liquid assets. This means you can get money from them without trouble. But savings accounts feel more ready to use day to day. You can take out your money from these accounts quickly when you need it.
Safety and Risk Factors
Money market mutual funds are often thought to be low risk. But being low risk does not mean there is no risk at all. These funds are investment products. They are not the same as bank deposits. Because of this, they do not come with protection from the Federal Deposit Insurance Corporation. Savings accounts are different. They are a kind of deposit product and do have federal deposit insurance up to certain limits.
The main risks in money market mutual funds are market risk and credit risk. These risks are small, but they do exist. The money you earn, or yield, will change over time. Your income from these funds is not fixed.
Some institutional money market mutual funds use a floating NAV. This means the value of your shares can go up or down, depending on market conditions.
Key risk points include:
- There is no coverage from the Federal Deposit Insurance Corporation.
- In rare cases, you could lose some or all of your money you put in.
- There is credit risk because of the people or groups who issue the products.
- During market stress, there can be fees for getting your money out, or it might be hard to take money back.
Even when you think about these things, money market mutual funds are still one of the more careful investment options for people who need a place to keep cash for a short time.
Types of Money Market Mutual Funds Available in India
There are many types of money market funds. The type you pick matters because what the fund owns, how you use it, and how it is taxed are not the same. The data shows how retail and institutional choices are different from each other. You will also see how some are taxable, and some are tax-exempt. It also talks about government money market funds and municipal funds.
If you are thinking about mutual funds in India, there is something important to know. Not every mutual fund for short-term cash is the same. Some of them act like liquid funds. Others are made for people based on their type and income tax needs. You should look at these things before you choose.
Liquid Funds
Liquid funds are known as short-term funds that deal with cash. They use money market investments that focus on short duration securities. These funds are for people who want to get their money fast and who do not want big changes in value. They are not made for long-term growth.
A market fund like this will often hold good debt that ends soon. This low risk way makes the value of your investment stay steady. People use these market funds when they need a spot for emergency cash, a place to wait with their money, or cash they need for plans later.
Liquid funds are popular because they give you both access to your money and a way to earn some income. They are not made to beat top growth investments. Instead, they act as a good middle step between keeping cash with no return and being in riskier mutual funds. If you want to keep money for a short time, these funds can help.
Ultra Short-Term Funds
Ultra short-term funds are much like money market options. They mainly invest in short-term debt and help with cash management. These funds use money market securities and other high-quality things that have short maturities.
These funds can be good for people who want to invest for a short time, but not just for one night. These funds are made to give stability and easy access to your money. They might act differently than a pure money market fund because of what they hold and how long those things last. So, you need to understand what kind of market fund or money market fund it is before you put your money in. Your investment horizon is important too.
Among the many types of money market funds, this group is good for people who want to put their cash somewhere safe for a short time. You do not move your money into longer-term bonds. If you want more flexibility and are okay with only a small return, you might want to look at these ultra short-term strategies. It is good to compare them with other types of money market options if this fits what you need.
Money Market Funds for Specific Investor Types
Not every money market fund is right for every person. Some money market funds work best for individual investors. Others are made for big companies. This can change the price you get, how you can use the fund, and how steady the share value will be.
The gathered details show these main groups made for investors:
- Retail money market funds are made for individual investors.
- Institutional investors’ funds can use a floating NAV.
- Government money market funds keep assets backed by the government.
- There are taxableand tax-exempt options you can pick, depending on your income needs.
If you want to pick the best money market fund, first check who the fund is made for and what is in it. A lot of individual investors go with retail money market funds. They do this because these funds try to keep their NAV at $1. If you care most about safety, you may want to look at government money market funds.
Choosing Between Money Market Mutual Funds and Savings Accounts
Choosing between money market mutual funds and savings accounts depends on how you want to use your cash. Both are good short term investment options, but they help with different things. A savings account gives you easy banking and the safety of deposit coverage. A money market mutual fund lets you try to earn more by putting your cash in the market.
Your choice should depend on your need for access, how you feel about risk, and market conditions. If you want to know more, look at who will likely get the most from each option.
Investors Suited for Money Market Mutual Funds
Money market mutual funds are good for people who want to keep their money active but do not want the big ups and downs of stocks or most debt funds. If you want to keep your money safe, easy to use, and get a bit of income, these funds may work well for you.
They are good for people who want a home for money for a short time. It can be for an emergency fund, buying something, or holding a balance in a brokerage account. A market fund can help you if you want a better return than a regular savings account gives.
You may be a good fit if you:
- Need to get cash when you want, but do not need all the daily banking tools.
- Want a more careful way to invest with short term debt funds, not longer-term debt funds.
- Are okay with low risk when you put your money in, and you know the rate can go up or down.
- Have short term goals instead of goals that are all about growth.
In short, they be best for handling cash. They do not really help to build wealth.
When Savings Accounts Make More Sense
Savings accounts are great when you want things to be easy. A savings account is a good choice if you want a bank account that connects with your everyday money. You can move your money fast, see your balance at any time, and keep your cash in deposit accounts you already know.
They are also a good place to keep an emergency fund if you want your deposit to be safe. The information shows that bank products may have things like ATM access, overdraft help, and insurance protection. These are things that money market mutual funds do not offer. For many people, this makes them feel more safe and helps them every day.
Yes, you might get lower returns with savings accounts, but you get more peace of mind. This is a good deal if you need the money to be safe, easy to get, and not mixed up with your other investing choices. If you care more about safety than getting a high return, savings accounts can be the best way to go.
Conclusion
To sum up, it is important to know the differences between money market mutual funds and savings accounts when you want to make smart choices about your money. Both money market mutual funds and savings accounts have their own features, benefits, and downsides. They work for different people who may want different things and feel different about taking risks. Money market mutual funds may offer higher returns and give you more flexibility when investing your money. A savings account, on the other hand, usually gives you safety and lets you get your money quickly when you need it. You should think about your financial goals, how much risk you want to take, and how easy you need it to be to get your cash. This will help you pick the right choice for you. If you want to get more control over your money, you may want to talk to our experts for a free consultation so you can look at your options.
Frequently Asked Questions
Are money market mutual funds suitable for short-term investment goals?
Yes, money market mutual funds can be good for short term goals. These funds are made for a short investment horizon and keep risk low. They try to hold their value and provide a modest rate of return. If you want cash management, money market mutual funds may work well. They are not meant for long-term growth.
What is the expected return on Indian money market mutual funds?
The gathered facts do not show a clear expected return for the Indian market. In the money market, mutual funds often earn a changing rate of return. This return moves with the interest rate, the kind of fund, and what is held in it. The rate of return is usually low and can go up or down when market rates change.
How liquid are money market mutual funds versus savings accounts?
Money market mutual funds let you get your money fast because they keep liquid assets. They often make it easy for you to take money out. Savings accounts are also good. You can use your bank to get your money, which can feel simple and quick. Both money market mutual funds and savings accounts are easy to use when you need cash, but savings accounts might be better for daily use.

